
Where your credit stands
The short version
Your credit affects which loans you qualify for and what they cost.
- FHA: 3.5% down with a 580 score or higher, or 10% down with a score from 500 to 579.
- Conventional: Fannie Mae removed the fixed minimum score for its automated approvals in November 2025. Lenders can set their own minimums, and pricing improves as scores rise.
- VA: VA sets no minimum credit score. Lenders can set their own, and they differ, which is where a Mortgage Broker who compares lenders helps.
- USDA: USDA sets no minimum credit score. Its automated system weighs the whole file, and files it does not accept can be underwritten by hand.
Lenders order reports from all three credit bureaus and use your middle score. With two borrowers on a conventional loan, the lower of your two middle scores sets the price.
Small changes can make a difference. Pricing shifts at set score thresholds, so paying down a credit card before your credit is checked can sometimes move you into a better pricing tier. We look for those opportunities first.
Go deeper
What moves a score
- Payment history: on-time payments matter most.
- Card balances: lower balances are better. Keeping each card under about 30% of its limit helps.
- Age of accounts: older accounts help, so keeping old cards open helps too.
- New credit: new accounts and hard inquiries can lower a score temporarily.
Shopping for a mortgage will not seriously harm your score. Mortgage inquiries within a short period, 14 to 45 days depending on the scoring model, generally count as one.
Why 679 and 680 can price differently
Conventional pricing changes in score bands. Fannie Mae's price adjustments change every 20 points, from 639 and below up to 780 and above. A score of 679 falls in the 660 to 679 band. One more point places you in the 680 to 699 band, which can lower the cost of the same loan.
Private mortgage insurance is also priced in score bands, so the same improvement can lower the monthly insurance cost. FHA's mortgage insurance does not change with your score, but lenders still set their own score tiers.
Your mortgage score is not your app score
Free apps often show a VantageScore or a newer FICO version. Mortgage lenders have long used older FICO models, often called Classic FICO. Your mortgage score can be higher or lower than the number in your app.
This is starting to change. In 2026 Fannie Mae and Freddie Mac began a limited rollout that lets approved lenders use VantageScore 4.0 instead. Lenders outside the rollout still use Classic FICO.
Updating your report quickly
When you pay down a card or a bureau corrects an error, the update can take a month or more to appear. A lender can request a rapid rescore, which asks the bureaus to update much faster with proof of the change. Only a lender can order one, and it only reflects changes that have already happened. Ask us before you pay down any balance, so the money goes where it will improve your score the most.
See it with your numbers
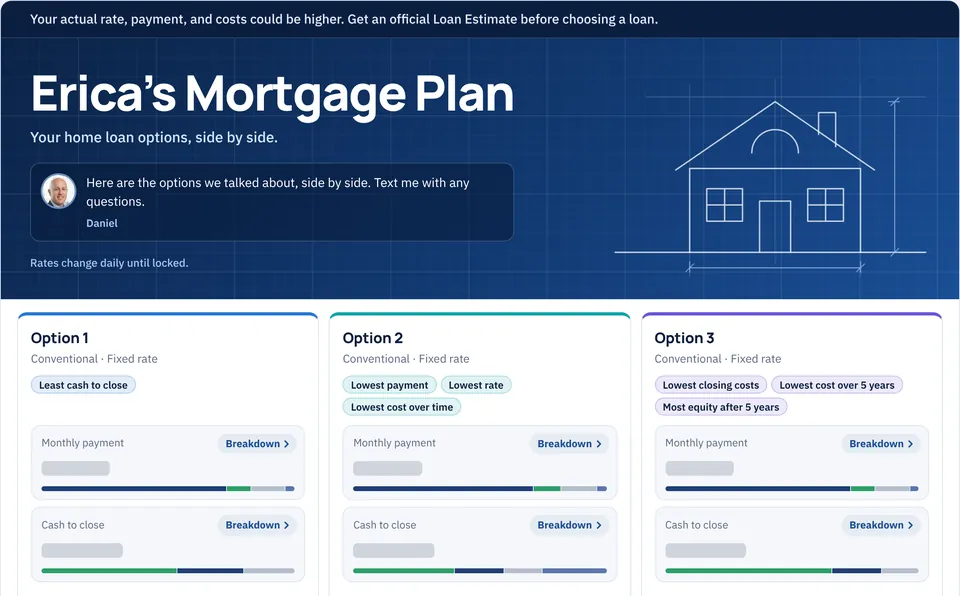
Your Mortgage Plan starts from the score range you share with Daniel. When you are ready to move forward, he orders your credit report with your permission, and the numbers firm up.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Step 3 of 14How much you need savedSaving for a home means cash for three things: the down payment, closing costs and a cushion. VA and USDA loans need no down payment at all.Go to step 3Leave the path: My credit needs some work
Sources
- CFPB: credit reports and scores
- CFPB: what kind of credit inquiry has no effect on my credit score?
- Fannie Mae Selling Guide B3-5.1-02: determining the credit score for a mortgage loan
- Fannie Mae loan-level price adjustment matrix
- Freddie Mac: credit score models and reports initiative
- Fannie Mae removes the minimum score for automated approvals (Nov 2025)
- VA underwriting standards, 38 CFR 36.4340
- USDA HB-1-3555, Chapter 10: credit analysis