
How much you need saved
The short version
You will need cash for three things:
- Down payment. Twenty percent avoids mortgage insurance, but it is not required.
- Closing costs and prepaids. These include lender, title and county fees, plus your first year of insurance and an initial deposit for taxes and insurance. Freddie Mac estimates typical closing costs at 2% to 5% of the loan amount.
- A cushion. This is money left after closing, called reserves. Some loans require reserves, and every homeowner needs them.
| Loan | Minimum down |
|---|---|
| VA | None, with full entitlement |
| USDA | None |
| Conventional | 3% for first-time buyers, 5% otherwise |
| FHA | 3.5% with a 580 score or higher |
If you qualify for a VA loan, it is often the best mortgage available to you. It needs no down payment and no monthly mortgage insurance, and it typically has the lowest rates, limited closing costs and flexible qualifying.
The money can come from savings, gifts from family, down payment assistance and seller credits toward closing costs. Your earnest money deposit also counts.
Rural purchases in Southwest Colorado often add upfront costs, such as a well water test, a septic inspection, sometimes a survey, and additional inspections for an older home. Earnest money is usually due within days of an accepted offer. Plan for a few thousand dollars beyond your down payment and closing costs to cover these early expenses.
Go deeper
Closing costs and prepaids, in plain terms
Closing costs are fees for the loan and the purchase, including the lender's charges, the appraisal and credit report, title insurance and settlement, and county recording. Prepaids are your own bills paid in advance, including the first year of homeowners insurance, interest from closing to the end of the month, and an initial deposit into your escrow account for taxes and insurance.
For example, a $300,000 home with 5% down has a $285,000 loan, and closing costs of 2% to 5% of the loan amount would be $5,700 to $14,250 before any credits. Seller credits, lender credits and gifts can cover some or all of that amount.
Reserves: the cushion
Reserves are the money you still have after closing, measured in months of your full house payment. For a one-unit home you will live in, Fannie Mae sets no minimum, although automated underwriting may still ask for some. Two- to four-unit homes require six months, second homes two months, and rental properties six months.
Checking and savings accounts and the vested portion of retirement accounts all count. Even when none are required, reserves strengthen a file and make the first year of ownership easier.
Gifts and the paper trail
On a conventional loan for a one-unit home you will live in, the entire down payment can be a gift from a relative, partner, fiancé or someone with a long-standing, family-like relationship. Two- to four-unit homes with less than 20% down require 5% from your own funds first. FHA, VA and USDA also allow gifts, each with its own rules on who can give.
The giver signs a letter stating the amount and that no repayment is expected. The lender then documents the money as it moves by check or transfer.
Lenders review two months of statements. A single deposit of more than half your monthly income needs a documented source. It is best to move money early, keep records and avoid depositing cash that cannot be traced.
Seller credits: how much they can cover
Sellers can pay some of your costs, up to each program's limit. They cannot pay your down payment.
| Loan | Seller can pay up to |
|---|---|
| Conventional | 3% with less than 10% down, 6% with 10% to 24.99% down, 9% with 25% or more (2% on rentals) |
| FHA | 6% of the price |
| VA | Normal closing costs, plus concessions up to 4% of the home's value |
| USDA | 6% of the price |
See it with your numbers
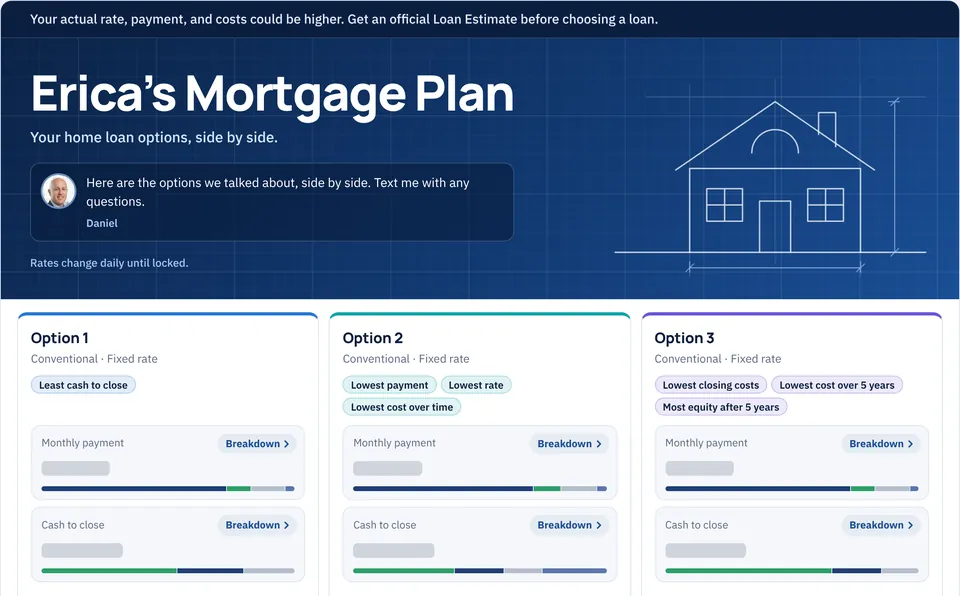
Your Mortgage Plan shows the exact cash to close for each option, with a breakdown of where every dollar goes.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Step 4 of 14Finding the money for a homeMoney for a home can come from everyday extras, a savings account that earns interest, gifts and assistance. VA and USDA loans need no down payment.Go to step 4Leave the path: I will need help with the down paymentI am a veteran or service member
Sources
- Freddie Mac: budgeting for upfront homebuying costs
- Fannie Mae Selling Guide B3-4.1-01: minimum reserve requirements
- Fannie Mae Selling Guide B3-4.3-04: personal gifts
- Fannie Mae Selling Guide B3-4.2-02: depository accounts
- Fannie Mae Selling Guide B3-4.1-02: interested party contributions
- VA: funding fee and closing costs