
Dropping mortgage insurance
The short version
- Conventional: ask your servicer in writing when your balance reaches 80% of the original value. It ends on its own at 78%. If your home has gained value, you may be able to remove it sooner with a new valuation.
- FHA: on most loans since 2013, it lasts for the life of the loan with less than 10% down, and ends after 11 years with 10% or more down. Refinancing into a conventional loan once you have enough equity removes it.
- USDA: the 0.35% annual fee lasts for the life of the loan.
- VA: no monthly mortgage insurance.
"Original value" usually means the lower of your purchase price or the appraisal when you bought. After a refinance, it is the refinance appraisal.
Go deeper
The rules for asking
Under federal law, you can ask to cancel conventional mortgage insurance at 80% of the original value if:
- You ask in writing
- Your payments are current and you have a good payment history
- You can show there is no second mortgage, if asked
- The home's value has not fallen below the original value, if asked
If you never ask, it must end at 78% on the original schedule, or at the midpoint of the loan term at the latest, which is 15 years into a 30-year loan.
Using today's value
If your home has gained value, Fannie Mae lets you ask for removal based on a new valuation. For a single-unit home you live in:
| Time since closing | Balance must be at or below |
|---|---|
| 2 to 5 years | 75% of today's value |
| More than 5 years | 80% of today's value |
| Any time, if your improvements raised the value | 80% of today's value |
You need no payments 30 days late in the past year and none 60 days late in the past two. The servicer orders the valuation, usually at your cost. Two- to four-unit homes need 70% after two years.
Leaving FHA mortgage insurance
Refinancing into a conventional loan is the usual way out. With 20% equity, the new loan has no mortgage insurance at all. With slightly less equity, conventional mortgage insurance may still cost less than FHA's, depending on your credit, and it can be removed later.
Veterans with an FHA or conventional loan should look first at refinancing into a VA loan. It removes monthly mortgage insurance at any equity level, and VA rates are typically lower than conventional rates.
Either way, the refinance has costs. Check the break-even before you decide.
See it with your numbers
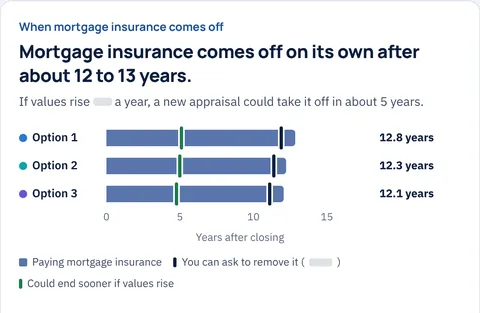
The mortgage insurance timeline in your Mortgage Plan shows when it ends for each option and what it costs until then.
Already have a Mortgage Plan? Open your link, or text Daniel.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Step 5 of 7Cash-out, or a second mortgage?A cash-out refinance re-prices your whole mortgage balance. If your current rate is low, a HELOC or home equity loan on top may cost less overall.Go to step 5Leave the path: I have FHA and want to remove MIShow me other reasons to refinance