
Renovation loans: buy and fix in one loan
The short version
A renovation loan combines the price of the home and the cost of repairs into one mortgage. The repair money is held in an account and paid to contractors as the work is done and checked.
Which one fits depends on the size of the job and the loan type you qualify for.
| Program | Good for | Repair limit | Finish within |
|---|---|---|---|
| FHA Limited 203(k) | Non-structural repairs | Up to $75,000 | 9 months |
| FHA Standard 203(k) | Structural work and larger jobs | $5,000 minimum, with a HUD consultant | 12 months |
| HomeStyle Renovation | Jobs of any size, including additions | Up to 75% of value | 15 months |
| CHOICERenovation | Jobs of any size | Up to 75% of value | 450 days |
| CHOICEReno eXPress | Smaller updates | 10% of value, 15% in some areas | 180 days |
| USDA purchase and repair | Eligible rural areas, nothing down | USDA and lender rules | Set by the lender |
| VA renovation | Eligible veterans | Set by the lender | Set by the lender |
Every program requires signed, itemized bids before closing, and most limit doing the work yourself.
Building seasons are short at our elevations, and good contractors are often booked months ahead. It is wise to get bids early and allow for snow in the schedule, since every program has a deadline. For manufactured homes, HomeStyle allows repairs but no structural changes, and caps renovation money at 50% of the finished value.
Go deeper
FHA 203(k): Limited or Standard
Limited 203(k) covers non-structural work up to $75,000, such as a roof, furnace, kitchen, flooring or paint. A consultant is optional, and the work must be done within nine months.
Standard 203(k) handles structural work, additions and larger budgets, with at least $5,000 of repairs. A HUD-approved 203(k) consultant writes up the work and inspects each draw. If you cannot live in the home during the work, up to 12 months of payments can be built into the loan.
Both follow FHA's rules: 3.5% down from a 580 score, FHA mortgage insurance, and a home you will live in.
HomeStyle and CHOICERenovation
These conventional options work for homes you live in, second homes and some rentals.
- HomeStyle Renovation (Fannie Mae): repairs up to 75% of the lesser of price plus repairs or the finished value. As little as 3% down on a fixed rate when a buyer is first-time or uses HomeReady. Up to half the repair money can be paid out at closing, and do-it-yourself work is capped at 10% of the finished value on one-unit homes.
- CHOICERenovation (Freddie Mac): up to 75% of value, with 450 days to finish. CHOICEReno eXPress covers smaller jobs within 180 days.
- HomeStyle Refresh: energy, water, resilience and disaster-repair work, up to 15% of the finished value, within 180 days.
USDA and VA
USDA purchase and repair adds repairs to a no-down-payment USDA loan in eligible areas. Non-structural jobs up to $35,000 do not need a separate inspector. See USDA loans.
VA renovation lets eligible veterans add repairs to a VA purchase, through lenders who offer it. Limits and timelines vary by lender, and the home must meet VA's property standards once the work is done.
What every renovation loan needs
- Itemized, signed bids from licensed and insured contractors, line by line.
- A contingency reserve: extra money set aside for surprises. Unused money usually goes toward your loan balance.
- An "as completed" appraisal based on the plans and bids.
- Draws: contractors are paid in stages after each phase is inspected.
The lender reviews bids and plans before closing, so allow a little more time than for a standard purchase. You can read more about lining up the work in contractors and draws.
See it with your numbers
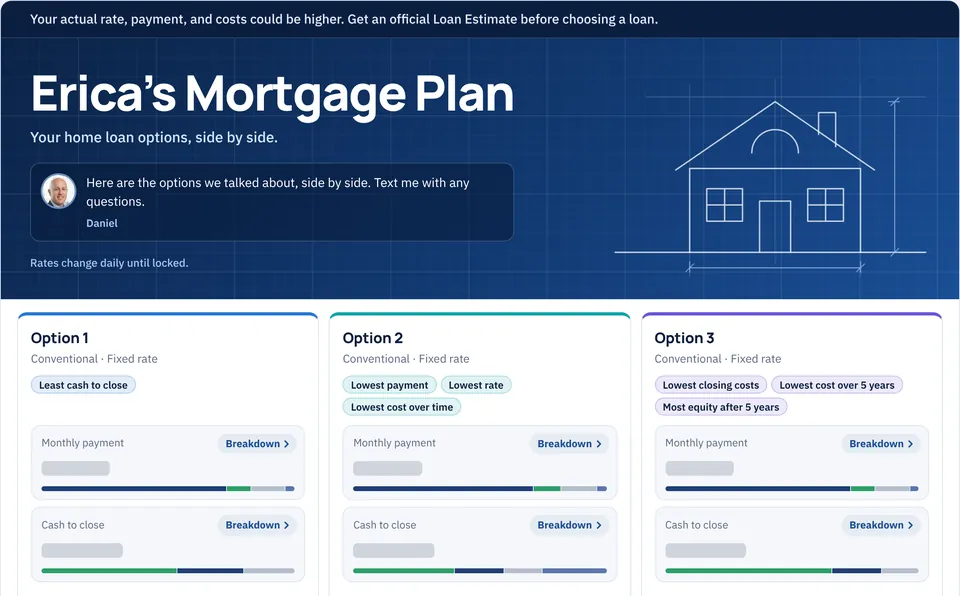
Your Mortgage Plan compares conventional, FHA, VA and USDA loans. For a renovation loan, Daniel can show the payment and cash to close with the repair budget added to the loan amount.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Stage 4: Finding the homeContractors, bids and drawsA renovation loan needs a signed, itemized contractor bid before closing. After closing, repair money is paid out in draws as work is inspected.Read the lessonOr go another way: Is it a fixer-upper or just dated?Continue in order: Getting pre-approved