
Why VA loans usually win, and who qualifies
The short version
If you qualify for a VA loan, it is often the best mortgage available to you. VA loans are for veterans, service members, National Guard and Reserve members, and some surviving spouses, and they combine advantages no other loan type offers:
- No down payment with full entitlement, as long as the price does not exceed the appraised value.
- No monthly mortgage insurance, at any down payment.
- Lower rates. VA loans typically carry the lowest rates of the four main loan types. In mid-October 2026, locked VA rates averaged about 0.36 percentage points below conventional rates.
- Limited closing costs. VA limits the fees a lender may charge you, and the seller may pay your closing costs.
- Flexible qualifying. VA sets no minimum credit score and no maximum debt-to-income ratio, and its residual income test looks at the money left each month after housing and debts, not only your debt ratio.
- Lasting value. There is no prepayment penalty, the benefit can be used again, and a future buyer can assume your loan.
In place of mortgage insurance, VA charges a one-time funding fee, usually added to the loan: 2.15% on a first use with less than 5% down. Veterans who receive VA disability compensation pay no funding fee.
To begin, you need a Certificate of Eligibility (COE). We can usually request it for you online, through VA's system for lenders.
Homes on acreage with wells and septic qualify for VA financing when they meet VA's property standards: safe, structurally sound and sanitary. Let us know early about a well, a shared road or a cistern so we can plan for the appraisal.
Go deeper
Who qualifies
- Serving now: 90 continuous days of active duty.
- Veterans who served since August 2, 1990: 24 continuous months, or the full period you were called to active duty if it was at least 90 days. Shorter service can count after a discharge for a service-connected disability or certain other reasons.
- Guard and Reserve: six creditable years, or 90 days of non-training active duty.
- Surviving spouses: generally those eligible for Dependency and Indemnity Compensation, or spouses of service members missing in action or held as prisoners of war.
Earlier service periods have their own rules. VA makes the final determination from your records.
The funding fee and other costs
| Down payment | First use | Later use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% or more | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
You pay no fee if you receive compensation for a service-connected disability (or would, but receive retirement or active-duty pay instead), have a disability rating before closing on a pre-discharge claim, are a surviving spouse receiving DIC, or are on active duty with a Purple Heart. If a rating comes later with an effective date before closing, the fee may be refunded.
On a purchase, the funding fee is the only cost you can add to the loan. Sellers can pay your normal closing costs, and VA caps other seller concessions at 4% of the home's value. Since August 2024, veterans may pay their own buyer's agent, although that fee cannot be financed.
Entitlement and loan size
Entitlement is the part of your loan VA guarantees. With full entitlement, VA sets no loan limit; the lender approves the amount based on your income, debts and credit.
If some of your entitlement is tied up in another VA loan, the remainder is calculated from the county's one-unit conforming limit, $832,750 in most of Colorado. If it does not cover a quarter of the new loan, a down payment is usually needed for the difference.
Entitlement can be restored when you sell the home and pay off the VA loan. VA also allows a one-time restoration if you have paid the loan off but kept the home.
The few cases where another loan comes close
For most eligible buyers, VA comes out ahead. The exceptions are narrow:
- A large down payment without a fee exemption. With 20% or more down, a conventional loan has no mortgage insurance and no funding fee, so the two can come out close. VA's lower rates often still give it the advantage.
- Saving entitlement for a future VA purchase, for example when you plan to keep this home as a rental and buy again.
- A home that does not meet VA's property standards as it stands. VA renovation financing can often solve this.
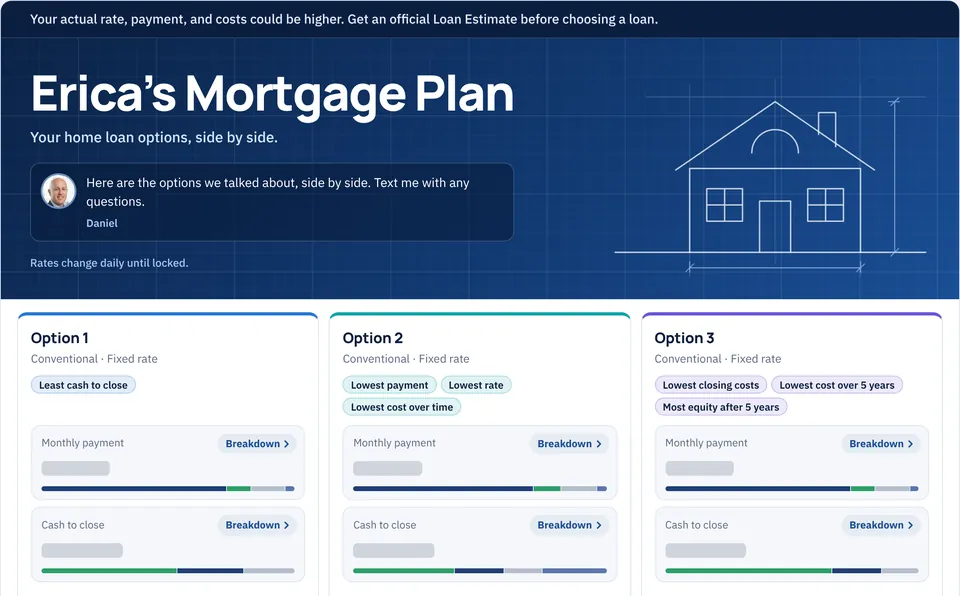
If you are exempt from the funding fee, VA is very difficult to match. Your Mortgage Plan shows the comparison in dollars.
See it with your numbers
Your Mortgage Plan shows your VA option, with your funding fee or none if you are exempt, beside your other options.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Step 2 of 7How much house can you afford?Your debt-to-income ratio compares monthly debts with income, and each loan type sets its own line. Your own budget should come first.Go to step 2Leave the path: The home is rural or on acreageThe home needs work