
Buying a home on acreage
The short version
Small acreage is common in Southwest Colorado, and conventional, FHA, VA and USDA loans all work on it for a home you will live in. These loans do not set an acreage limit. What matters is whether the property is a typical home for the area.
- Comparable sales: the appraiser needs similar homes with similar land nearby. In this area, they usually exist.
- Land value: when the land is a large share of the total, lenders look more closely.
- Residential use: a working farm or ranch does not qualify for a home loan. A few animals, a barn or a garden is acceptable.
- Outbuildings: shops and sheds are acceptable, and they add value when they are typical for the area.
- Access and water: legal, year-round access and a safe water source.
Around Mancos, Dolores, Cortez, Durango, Pagosa Springs and Norwood, a home on a few acres with a well, septic and a shop is common, and local appraisers are familiar with it. Long driveways, snow and mud season are also common, so confirm that access is legal and maintained year-round.
Go deeper
Access and roads
Lenders look for legal access, usually a public road or a recorded easement, and a way in all year. Your title commitment shows the easements on record.
If the home is on a private or shared road, find out who plows and repairs it and who pays for that work. A written road maintenance agreement is often required, and it protects you in either case. Ask your agent for it early, along with any HOA or road association documents.
Water rights, minerals and surveys
Colorado contracts include deadlines to examine water rights and mineral rights. It is worth using them.
- Well permit: many wells on lots under 35 acres are permitted for household use only, which means indoor use with no outdoor watering. Domestic and livestock wells, usually on 35 acres or more, can water up to one acre of lawn and garden, as well as livestock.
- Ditch and irrigation rights: these may or may not come with the land. Any rights included in the sale should be written into the contract.
- Minerals: mineral rights are often owned separately. The title commitment shows what has been separated.
- Survey: a new survey or improvement location certificate shows where the property lines and buildings actually are.
When the land is the bigger story
Larger parcels can still work, but you can expect more questions. USDA states that the site cannot produce income, although a garden is acceptable. If the land earns income, such as from a hay or grazing lease, tell us at the start. Some loans can accommodate a small, typical use, and others cannot.
A second home on the same parcel, such as an accessory unit, changes the appraisal and the loan options. Vacant land is not eligible for these home loans at all.
See it with your numbers
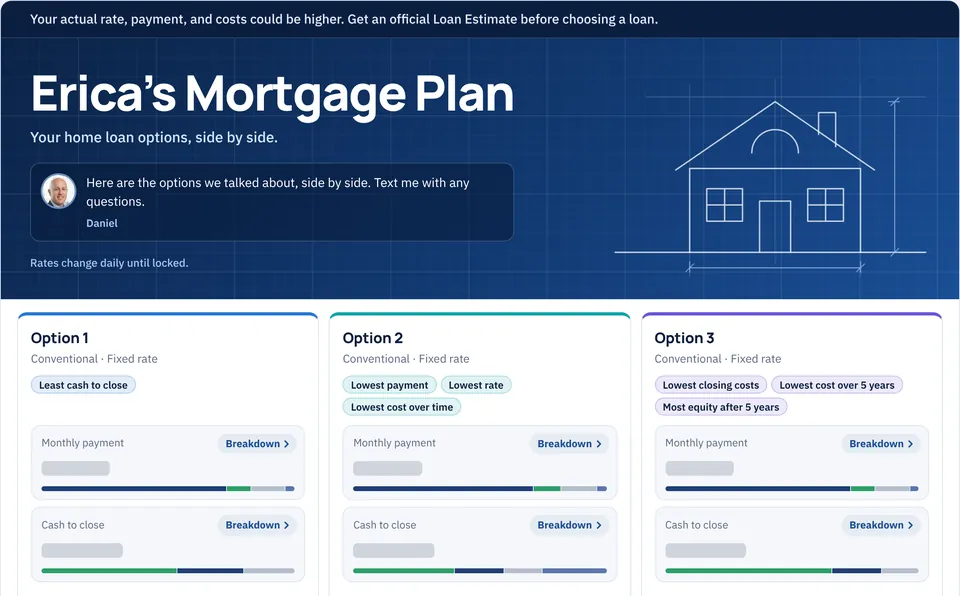
Your Mortgage Plan puts each loan type that fits the property side by side, with the payment and cash to close for each.
Already have a Mortgage Plan? Open your link, or text Daniel.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Step 2 of 6Wells, septic and waterYou can expect a water test, a septic inspection and proper distance between the two. Shared wells require a recorded agreement, and the well permit matters.Go to step 2Leave the path: The home needs workCould USDA work here?