
Rent or buy?
The short version
Buying is not automatically better than renting. It tends to be the better choice when you stay long enough for the equity you build to exceed the costs of buying, owning and later selling.
Owning costs more than the mortgage payment. It also includes property taxes, insurance, mortgage insurance, upkeep, and closing costs up front. In return, part of each payment reduces your loan balance, and any increase in value is yours. Rent pays for flexibility and freedom from repair bills, but none of it comes back to you.
Three questions settle most cases:
- How long will you stay? It takes years to recover the costs of buying and selling.
- How does the full monthly cost of owning compare with your rent?
- What else could your down payment do? Money in a house is not earning a return elsewhere, and it is not easy to access.
In resort towns such as Telluride, Durango and Pagosa Springs, long-term rentals can be scarce and expensive, which can favor buying if you plan to stay. In rural areas, owning brings costs that renters never see, such as well and septic upkeep, propane, and road and snow maintenance. Include those costs in your comparison.
Go deeper
The full cost of owning
- Monthly: principal and interest, property taxes, homeowners insurance, mortgage insurance and any HOA dues.
- Upkeep: a common rule of thumb is about 1% of the home's value a year. Older homes and rural systems can cost more.
- Up front: closing costs, often 2% to 5% of the loan amount.
- When you sell: selling costs, such as agent fees, title and closing costs. These costs are negotiable, but they are real.
Only the principal portion of your payment builds equity. In the early years of a 30-year loan, most of each payment is interest.
How equity grows, and shrinks
Equity comes from two sources: paying down the loan and changes in value. Borrowing magnifies both. For example, if you buy a $300,000 home with $15,000 down and values rise 3%, your equity grows by $9,000, a 60% gain on your down payment. If values fall 3%, you lose the same $9,000.
Values do not rise every year, and no one can promise they will. The home should still work for you if prices stay flat.
Taxes
Mortgage interest and property taxes are deductible only if you itemize. Many households take the standard deduction instead, so the tax benefit may be smaller than you expect, or there may be none at all.
When you sell a main home you have lived in, much or all of the gain may be tax-free under federal rules. A tax professional can tell you what applies to you.
When renting wins
- You may move within a few years.
- Your job or income is uncertain.
- Buying would use up your savings.
- Rents where you want to live are low compared with prices.
- You need time to build credit, which can lower what you pay later.
Renting for now is not a failure. A year spent building credit and savings can help you qualify for a better loan.
See it with your numbers
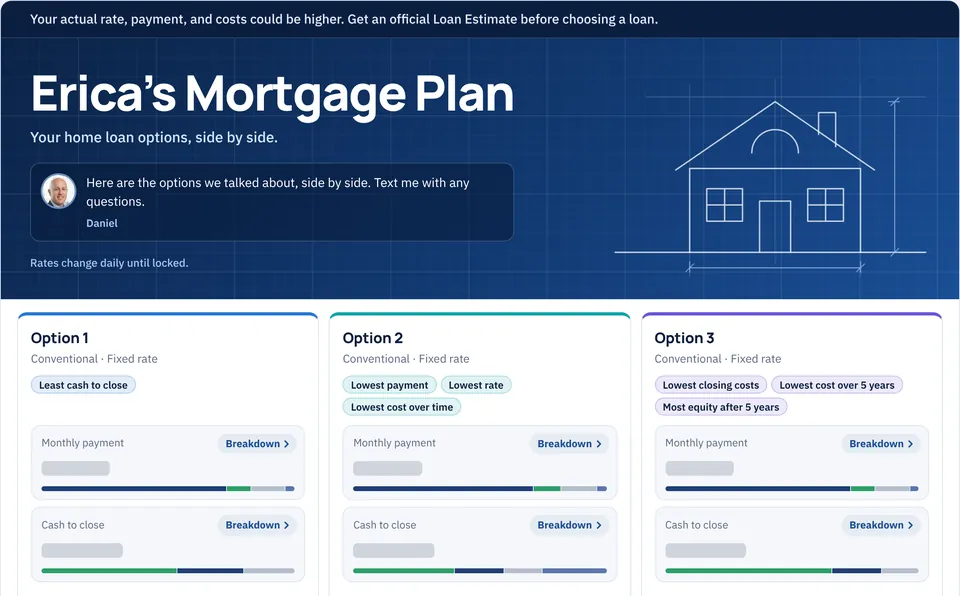
Your Mortgage Plan shows the full monthly payment for each option and what each costs over 3, 5, 7 and 10 years. The rent or buy calculator in this lesson sets owning beside your rent.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Lesson 7 of 7 in Am I ready?Are you a first-time buyer?A first-time buyer usually means no home owned in the past 3 years. It allows 3% down on a conventional loan and can require a homebuyer class.Read the lessonOr go another way: Renting a while longer makes sense