
Is it a fixer-upper, or just dated?
The short version
Lenders care whether a home is safe, sound and livable. Old carpet and dated cabinets do not matter to them. A failing roof, a broken furnace, exposed wiring or a lack of working water do.
When a home has problems like these, you have three choices: ask the seller to fix them, decide not to buy, or use a renovation loan that pays for the repairs as part of your mortgage.
A renovation loan is based on what the home will be worth after the work. This can make a fixer-upper possible when your limit is cash rather than income.
The size of the job matters. Finishes and systems, such as a roof, furnace or kitchen, fit the lighter programs. Structural work, additions and layout changes require the larger ones. The scope of work determines which loan fits.
Short building seasons and busy contractors are a real factor in Southwest Colorado. A roof or septic replacement identified in November may not be completed until spring, which affects which loan works and when you can close.
Go deeper
Dated, worn or unsafe
- Dated: old finishes, paint and flooring. Any loan works, and these can be updated later on your own schedule.
- Worn: systems near the end of their life but still working, such as an old water heater. These are worth a credit or a lower price, and a line in your budget.
- Unsafe or unlivable: a leaking roof, no heat, faulty wiring, a failed septic system or structural damage. FHA, VA and USDA appraisers will require repairs. A conventional appraisal can also come back "subject to" repairs.
Only the last group requires a decision before closing.
Before you offer on a fixer-upper
Have a contractor walk through the home during your inspection period and give you a rough estimate. Check the county's permit history for past work. Consider how long you can live with the project, and whether you can live in the home at all while the work is underway.
Renovation loans take longer to close than standard loans, because bids, reviews and sometimes a consultant come first. Ask for a closing date that allows for this. A seller who needs to close in three weeks may not be the right seller for a renovation loan.
Small items: repair escrows
Not every repair needs a renovation loan. When the work is small or the weather will not allow it before closing, such as exterior paint in January, some lenders allow funds to be held back at closing and paid out when the work is finished.
Holdbacks have limits and deadlines that vary by loan and lender. They are meant for a short list of items and are not a substitute for a renovation loan. Ask us before you rely on one.
See it with your numbers
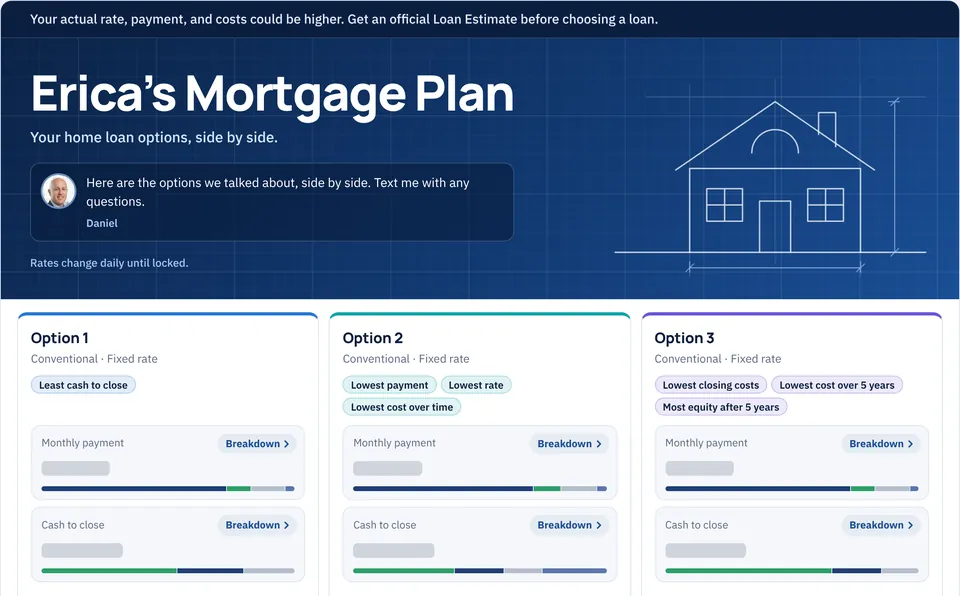
Your Mortgage Plan can put a renovation loan beside a standard loan, with the payment and cash to close for each.
Already have a Mortgage Plan? Open your link, or text Daniel.
Back in your Mortgage Plan, see this with your own numbers.
Your next step
Step 2 of 5Renovation loans: buy and fix in one loanOne mortgage can cover the home and the repairs. Compare FHA 203(k), HomeStyle, CHOICERenovation, USDA and VA options by job size and limits.Go to step 2Leave the path: I know the loan. How do bids and draws work?